The Fed Held Rates Steady. The Real Shift Was in the Dot Plot.
The Federal Reserve left its benchmark range at 3.5% to 3.75% on June 17, 2026, but officials quietly moved their median rate path higher through 2028. For borrowers and investors, the bigger message was not patience. It was that relief still looks farther away than it did in March.
The Federal Reserve's June 17, 2026 statement did what markets broadly expected on the surface: it kept the federal funds target range at 3.5% to 3.75% in a unanimous 12-0 vote. But the more important move was hiding in the new projections. Officials pushed their median end-of-year rate path up to 3.8% for 2026, from 3.4% in March, and they also moved 2027 and 2028 higher. The Fed did not raise rates on Wednesday. These individual projections are conditional assessments, not probabilities of future decisions or a commitment by the Committee.
Video Link
FOMC Press Conference, June 17, 2026
This provider does not render reliably inside PanoramaDigest. Open it directly on Federal Reserve.
Watch on Federal ReserveFederal Reserve — FOMC Press Conference, June 17, 2026
The official Federal Reserve press-conference page gives readers the full post-decision video and a direct source path beyond the statement and dot plot.
That distinction matters more than the headline hold. By late afternoon, an Associated Press market report said stocks slipped after the projections showed more officials anticipating a possible hike later this year. In other words, Wall Street treated the meeting less like a non-event and more like a warning that the central bank still sees inflation risk as more dangerous than growth fatigue.
The official projections became the story
The clearest way to read the meeting is to compare June with March. Three months ago, the median path still implied a gentler descent. The June medians were higher across the next three years, but they did not establish a binding institutional baseline.
| Median federal funds projection | March 18, 2026 | June 17, 2026 | What changed |
|---|---|---|---|
| End of 2026 | 3.4% | 3.8% | The projected median rose; this was not a change to the current policy rate. |
| End of 2027 | 3.1% | 3.6% | Officials see less room to normalize policy quickly next year. |
| End of 2028 | 3.1% | 3.4% | The higher-for-longer message now stretches beyond a single year. |
| Longer run | 3.1% | 3.1% | The long-run destination was unchanged; the path to get there was not. |
Reading the numbers: The increase from 3.4% to 3.8% is 0.4 percentage points, or 40 basis points. The median is the middle projection, or the average of the two middle projections. Individual projections depend on each participant's economic assumptions and assessment of appropriate policy.
That is why the hold should not be mistaken for reassurance. When the policy rate stays put but the expected path moves up, the central bank is effectively telling markets that it sees more persistence in inflation pressure or more resilience in the economy, or both. PanoramaDigest made a similar point after the surprisingly strong May jobs report: the labor market was making the rate story harder, not easier. Wednesday's projections suggest that view has hardened inside the Fed.
The statement sounded steady, but not relaxed
The wording of the statement helps explain why. The Committee said economic activity was expanding at a solid pace even with elevated uncertainty tied in part to the conflict in the Middle East. It also said productivity growth and capital investment were strong, job gains were keeping pace with the workforce, and unemployment had changed little. That is not the language of a central bank preparing readers for imminent relief.
Just as important, the Fed said inflation remained elevated relative to its 2% goal and cited supply shocks, including energy, as part of the reason. That combination matters for households because it keeps the pain split in two directions at once: fuel and other essentials stay expensive, while mortgages, auto loans, credit cards and business borrowing remain expensive as well. A hold can feel neutral on television. In the real economy, it often means high prices and high financing costs are still arriving together.
- 2:00 p.m. EDT, June 17: the Fed left the target range unchanged at 3.5% to 3.75%.
- At the same release: the projections lifted the 2026 median funds-rate path to 3.8% from 3.4% in March.
- Minutes later: traders focused less on the unchanged decision and more on the possibility that the next meaningful move is not down.
What the meeting means outside the trading floor
For borrowers, these June projections did not guarantee any particular future loan rate. They should not be treated as a current financing quote or a personal borrowing recommendation. For employers, especially those already juggling wage pressure and costlier inventories, the meeting reinforced that capital still has to clear a high hurdle. For investors, the issue is more nuanced. Higher rates can restrain valuations, but they also reflect a Fed that still sees real momentum in the economy. The problem is that momentum is no comfort if it arrives with renewed inflation stickiness.
That is where the June meeting gets more interesting than a standard rates story. The Fed is not describing an economy on the edge of contraction. It is describing one that remains active enough to keep policymakers cautious even after several months of waiting. In plain English, this was a meeting about stubborn strength. Consumers, businesses and markets may want rate relief; the central bank is signaling that the economy has not yet earned it.
Readers who want the clearest source trail should start with the official statement, the projection materials, and the Federal Reserve's press-conference page. The headline hold was real. The quieter shift in the dot plot was the part markets could not ignore.
Clarification, September 23, 2026: This article now distinguishes individual, conditional rate projections from probabilities and Committee commitments. The original publication date and reported projection values are unchanged.
Read Next
Related Stories
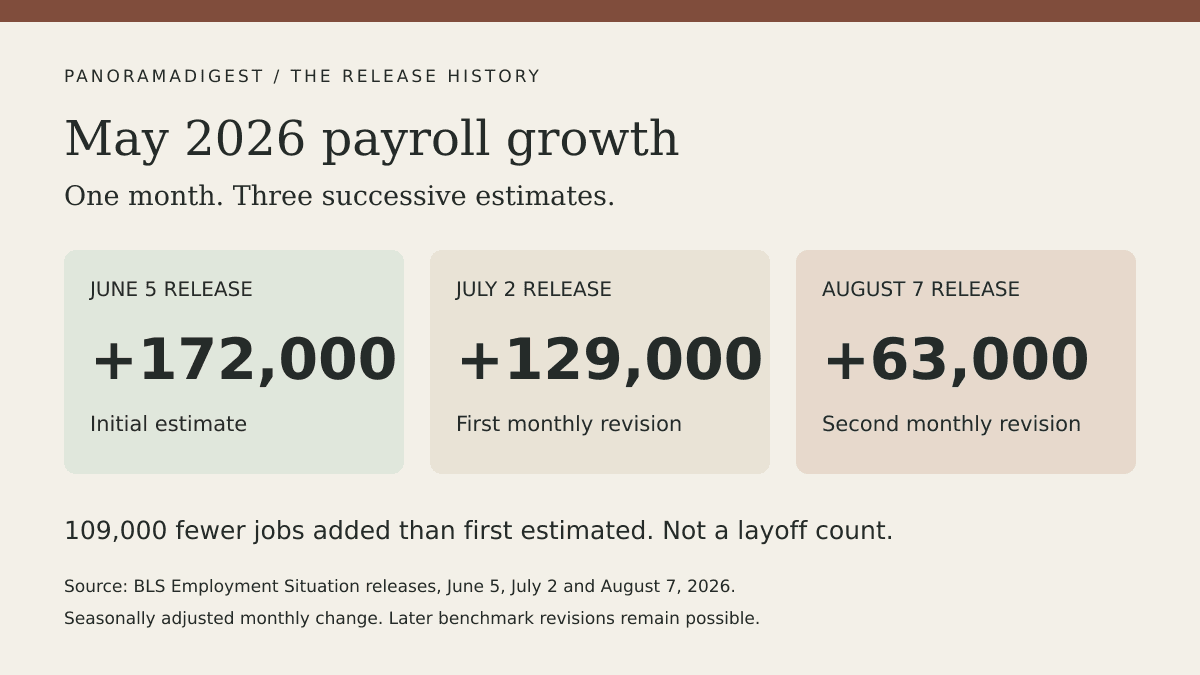
May 2026 Jobs Report Revisions: From 172,000 to 63,000
Trace May 2026 payroll growth through three BLS estimates, a 109,000 downward revision and the distinction between rate expectations and the Fed decision.
China Q3 GDP Growth Rebounds to 4.5%: Retail and Investment Still Lag
China's Q3 GDP rose 4.5%, but September retail sales and nine-month investment show an uneven recovery. A guide to the figures, periods and price bases.
2027 Social Security COLA: The 3.6% Increase in Dollars and Payment Dates
The 2027 Social Security COLA is 3.6%. Our worked examples separate the gross increase from the bank deposit, with the official calculation and payment timing.